Cheer Good Cheer

Good Cheer! Not just a holiday greeting on the south half of Whidbey Island. Good Cheer is a food bank, thrift shop, garden, and – the folks I’m more familiar with – a group of gleaners: the Good Cheer Gleeful Gleaners, a group of volunteers who harvest fruit from willing residents’ trees.

Me strategically positioned waiting to load the truck.

Me strategically positioned waiting to load the truck.

They had a potluck this afternoon (which is why I’m typing so late on a Saturday night). There were tales of abundance and want that become entwined as free food is delivered to people who need it. It is such a simple idea, and yet, can be so hard to implement when it is more than apples, pears, and plums.

Fruit trees are so popular that the fact that I have four of them in my backyard is considered a selling point. They produce lots of flowers, shade, and sometimes people even eat the fruit. For Sale - alas Most times they don’t. The deer and the yellow jackets are happy to devour the rest, but most fruit ripens and falls without being used. If anything, homeowners can find an abundant harvest means a messy lawn. Enough folks pick their crop to spawn a flurry of dessert photos and recipes on facebook every autumn. But many more are mowing apples when they mow the grass.
I’d like to give credit to the person who came up with the idea, but it is an egalitarian group. No one claims the spotlight. (The local paper probably did all the right research.) The idea is simple. Every year, they compile an expanding list of trees. Scouts check for ripeness. A coordinator finds an agreeable owner and then cajoles a small crowd to gather to gather. The fruit is separated into ones that look ready for a store, ones that are more rustic, and ones that are fed to less picky sheep and goats. There’s more than enough supply. There’s more than enough demand. The limiting resources are gleaners and storage.

The part about there being more than enough demand sunk in yesterday. Good Cheer’s Facebook page included a post that included this quote.
“We have served over 1,000 in the month of November and we still have one more day in this month. In the past 2 months, over 110 families who have not used the Food Bank this year or ever before came through our doors to ask for help with food.”
They were talking about the Food Bank, which supplies much more than gleaned fruit. It is an impressive operation. Those numbers impressed me. More than 1,000 families. 110 families that hadn’t used the Food Bank before. That doesn’t sound like a recovering economy.

A few minutes later, a factoid percolated back from memory. After a bit of research I confirmed what I remembered, and I had to respond.
“The number of people you feed just sank in. According to the census, South Whidbey only has about 17,300 people (Clinton + Langley + Freeland + Greenbank). If the average household is close to two people, then you’re feeding over 10% of the south half of the island. Is that true? Amazing, sad, and a mix of emotions.”

Later, the implications expanded. (Unfortunately, I was in the shower, which made it difficult to scribble notes. It is late enough tonight that I had to give up my research foray. Enforced conciseness.)

There’s enough demand for the food. There’s enough supply (especially considering how much food we waste.) There’s always a constraint. For the gleaners it is getting enough people and finding enough storage. (I don’t know if the Food Bank’s overall supply has a surplus, and don’t know their constraints.)

There are too many people without enough. Enough food, clothes, housing. We know there is a demand.

One of Good Cheer’s other success stories are their Thrift Stores. In the dichotomy that is South Whidbey’s economy, there are a lot of people proudly wearing donated clothes. I go there for household stuff that works fine even if it has a scratch or is an off color. Demand and supply meet, but not always in my size.

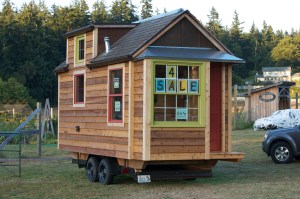
There are over 14,200,000 vacant homes in America. There are less than 700,000 homeless people. I am glad to see that the number of homeless isn’t higher. What keeps us from finding some way to open a few percent of those vacant homes, or let people build smaller, more affordable houses? Cabin by Angela So many homes on South Whidbey are vacation homes that neighbors meeting new owners are very likely to ask, “So, are you a snowbird, a weekender, or will you actually live here?” Some neighborhoods, especially in winter, seem to drop to 25% occupancy. Yet, people are living in the woods because they can’t afford housing, and because there is no homeless shelter.
South Whidbey prides itself on being an open and accepting community. Some people living here travel the world giving classes in how to build community. Yet here we are, a microcosm of the American macrocosm. Over 10% of the population needs the Food Bank. How many more need food stamps? How many are homeless? How many are unemployed, or barely getting by? We have the resources. There’s enough wealth of money and spirit. Yet, lack persists.

If a place like South Whidbey, with its wealth of enlightened millionaires and a passionate volunteer population, can’t feed and house everyone then how can anyone expect such a large community as a county, state, or country to succeed?

Maybe what it takes is seeing something like Good Cheer as a very good and necessary first step, something to celebrate; but more importantly, something to replicate and emulate. Here, maybe it can be a model for more than food. In those other places that don’t have food banks, thrift stores, and gleaners, maybe Good Cheer can be cheered as a good example.
Posted in Uncategorized | Tagged , , , , , , , , , , | Leave a comment

Thanksgiving 2013

A short and random list of thanks:

Most prominent considering Monday’s meeting: Thanks to whoever pushed for and passed the homeowner protection regulations and legislation

And then, thanks to:

  • The flora and fauna that sustain me
  • Friends and Family that support me
  • Good health
  • People who know how to have fun
  • Everyone who made it possible for us to share without traveling
  • Everyone who made it possible for people to travel and visit in person
  • The power that’s on
  • The water that’s clean
  • The air that is clear (after I finally got the fire to catch – hmm)
  • The folks that taught me the fun of frugality
  • Drew, who I hope is taking a day off
  • That I remember my katas (and thanks to Sensei for teaching them and everyone else for helping me practice them)

and much more, but why bore you with a list that could go on ad infinitum?

I’ve been asked “How do you keep your spirits up while going through what you’re going through.” (massively paraphrased, of course) I assume everyone has their ups and downs, their own battles regardless of appearances and I assume we’re all doing the same thing, but if not – even when there’s bad, there’s also good. Maybe it’s standing off to the side, but it is there, somewhere.

I’m not talking about the “closed door, open window” mantra. When I pull a bill from the mailbox I look around at the world. If something unseemly is happening financially, I remind myself that the scenery may be even more appealing. If I watch a stock go down, I remember the compliments I’ve received for my writing. If something uncomfortable is happening in one area, I don’t ignore it; but, I do remind myself that nothing in my life is everything in my life. I don’t always succeed. Sometimes it takes hours to remember to pick a different perspective, then I feel foolish for not having done so earlier.

I haven’t been able to will my problems away, but I have been able to tip the balance back by tipping my point of view.

An exercise we played at the Thanksgiving table was, “What would be different, while sitting at the table, if you were worth ten million dollars?” I’m happy with the friends who were there. The food would be almost exactly the same. There’d be no need for a fancier house, or a nicer neighborhood. At that moment, I was as rich as I needed to be, and millions wouldn’t change that.

And now, hours later, there are dishes to wash and food to put away and an evening without work. And, of course, one of the best things about Thanksgiving: a toasted turkey and cheese sandwich with a glass of the remaining wine, and sending out good wishes to you all.

That’s more than enough to give thanks for. Thanks. And, thanks for reading.

Focus on the brightness, not the darkness.

Focus on the brightness, not the darkness.

Posted in Uncategorized | Tagged , , , , , , | Leave a comment

Mesmerizing Mortgage Mediation Meeting

Well, that certainly didn’t go according to plan. Housing limbo continues. Today was the long awaited and comically delayed mediation meeting with the mortgage company. Finally, I’ve got enough work to make enough money to pay my mortgage, but would they agree? The arithmetic suggested they should say yes; but, the process has been irrational enough that any answer was possible. So, what happened? Something none of us in the room expected. Puzzle this one out. My account is closed and I’ll get more time to prove I can make my payments. If those two sound contradictory, congratulate yourself on your cognitive ability.

Thanks to the wonders of blogging, I don’t have to belabor everyone with the entire history of my personal mortgage crisis. Between tags, keywords, and categories (check: mortgage) you should be able to step back through the story. For those not comfortable doing such things, here’s the quickest version. I stopped paying my mortgage about a year ago because my investments were almost totally depleted. Since then the discussion with the mortgage company has been – illustrative of business tactics I’ve never witnessed before. Fortunately, Washington State makes counselors available, and they’ve maneuvered me into the mediation process that forestalls the foreclosure process, hopefully long enough for me to find or make enough money to pay a modified mortgage. Today was supposed to be that meeting.

Skipping the suspense, there was yet another classic miscommunication. I was there. My counselor was there. The mediator was there. The mortgage company’s lawyer was there. The mortgage company wasn’t. A half hour of phone calls later we learned that the mortgage company had “closed out the account” less than a week ago, and therefore there was no one assigned to my case. Evidently they didn’t tell anyone, not even their own lawyer.

For those following the folly, you may notice a trend. This is the meeting that was held because the previous meeting was convened without informing me, which invalidated that meeting. That meeting was held because the previous meeting had two different meeting times. My counselor and I were told to show up in the morning. Everyone else was told to show up in the afternoon. Hard to have a discussion that way.

So there I sat, somewhat aware of the standard foreclosure process thanks to my counselor and a bit of research, and confused because I’d never heard of an account being closed. Was that one step closer to foreclosure? Evidently not. Is it encouraging? No. Is it reversible? Evidently, though I still don’t know how it gets reversed and by who.

What I was pleased about was the professional manner of everyone in the room. They agreed that the mortgage company would like to have three months of profit and loss statements, and several months of bank statements substantiating my income. The only way to do that is to give me more time. We already have the October data. We’re almost through November. Add in December, wait for checks to post, and submit a new package by early January and there may be no need for mediation – assuming the mortgage company re-opens the account, somehow. But hey, since we were all in the room, and we were all looking ahead, we decided to schedule yet another meeting (which costs me $200, and that’s okay.) Next best date is early March, just in case.

One consequence of having a scheduled mediation date is that the mortgage company can’t proceed with foreclosure while mediation is in progress. Effectively, my situation doesn’t change. I continue working hard, as I’d planned to anyway. My incentives for working on the house are somewhat contrary, so I’ll work on what I want or need to. Eventually, the mortgage company will present me with a bill or an option or a deal or who knows what other surprises they may present. Even though I think I have enough money in my account to make a payment, I don’t know what number to write on the check. A couple of months ago they sent me a letter stating that the offers they’d made were to be ignored because the payment calculations were incorrect and that they’d send me updated payment requirements – which I haven’t received.

The process works within a well-defined legal system, but considering what we learned in the meeting about the account being closed, I keep in mind that some bureaucratic machinery may yet be churning its away to posting a foreclosure notice on my door. Even if it is invalid, I’ll probably react emotionally, the real estate market may react, and interrupting the process will take time.

On the larger scale, the housing and mortgage crisis look unstable. On an individual basis, it isn’t much clearer. I feel sorry for anyone going through this who isn’t aware that counselors may be available, and that isn’t comfortable with finances, and that isn’t experienced in business negotiations. My anxiety level rises whenever I deal with my mortgage shortfall, and I have admirable support. What’s it like for someone without experience, education, or help?

Believe it or not, I’ve simplified the morning’s events. To adequately describe that one hour meeting would probably take all day. That’s one reason for this blog post. Calling all of my supportive friends and trying to answer every question would be a full time job. Step one is reminding people that this is a process that surprises and confuses the professionals that deal with it every day. Hopefully, this synopsis lays a good foundation, and provides some reassurance to others in similar situations.

My situation is one of the simplest: single guy, one house, one mortgage, and a beginning credit rating of about 800, now severely reduced. And yet, as the meeting closed, the mediator pointed out that the name Trimbath is a cause for entertainment in their office. Whether that is through meeting mishaps or some other story, I’m happy to give folks a reason to smile amidst the chaos – as long as I get to keep my house out of foreclosure.

Such a small house, yet such a large issue.

Such a small house, yet such a large issue.

Posted in mortgage, Uncategorized | Tagged , , , , , | 2 Comments

Simple Social Media Choices

Social media. We’ve got to come up with a better term for it than that. That’s like calling a dance party an “aerobics and conversation congregation”. Yes it may be correct, but “dance party” is a lot more fun. I’m teaching a class tomorrow in Social Media Strategies, basically a class for people who’ve cleared the hurdle of finally getting an account, but then don’t know what to do with it. Not a surprise. I didn’t know what to do with Facebook when I signed up in 2008. New technologies and new ideas are sometimes easiest to accept when people haven’t made up names for them yet, kind of like new friends are easiest to get to know if no one has told you what to expect from them first. There’s a lot of “new” coming our way. Maybe I shouldn’t listen to what folks have to say about it.

Open disclosure: I use Facebook (11 more friends and I hit 666), Twitter (@tetrimbath), LinkedIn (my profile, aka resume), Google+ (“plus me” – groan), and Pinterest (they say Pin me – groan again). I have accounts on several other sites, but there’s not enough time to keep up with all of them. They are wonderful and worthless and distracting and informative and free. I particularly like the free part. I’ve even got a good enough Klout score to generate an occasional freebie (a Perk.) I should get some free Hershey’s within a couple weeks.

They are not panaceas. They are not Pandora’s box. Collectively, they exert an influence that is usually subjective, but is just frequently lucrative enough to convince many people to exert great efforts trying to exploit them.

Congratulations. You’re already using social media. There’s no other way to read my blog (and yes, I consider emails and blogging to be social media, too.) Maybe you print it out, but either you or someone else received it electronically first. That’s the media part. The social part is that somehow, through some social networking within a few degrees of separation, you were provided with this copy. That doesn’t mean I like the term.

Life is simple. We make it complex. My life is complex, and I know who made it that way. Me. Fortunately, even though my life is complex, it is much simpler than it was a decade or two ago – as hard as that is to believe as I type this at 8pm on a Friday night.

Some people leading incredibly simple lives have very little time to simply relax. Ironic, eh? Simple doesn’t mean quickest.

It is too easy to spend too much time over-analyzing a life. Too many fall into the trap of over-examination because Socrates said, “An unexamined life is not worth living.” There’s also having too much of a good thing. The over-examined life isn’t being lived.

I could optimize my life for minimum impact on the planet (maybe I should move off-planet), for maximum justice for my fellow humans (hear ye, hear ye), for maximum profit (very Ferengi), for self-indulgence (hello Hedonism), for any of the causes that passionate people devote their lives to. I suspect that I shouldn’t take any of these to extremes, and that luckily human diversity ensures that each will have someone that will dive in with vigor.

There are many trends heading our way: environmental, political, spiritual, economic, technological, and cultural. It is impossible to understand, control, and embrace them all – regardless of how many TED Talks are watched.

I started using Facebook because someone required, er, strongly recommended it, prior to a gathering of fascinating people. Along the way I added LinkedIn, so my resume had another place to live. I added Twitter out of curiosity, and now find it fascinating as headlines break. I added Google+ out of curiosity, and have yet to find a good reason for it beside the Hangouts (which are cheap video teleconferencing and therefore handy, but not unique). I was drawn to Pinterest because people over there like photos, and I take and sell photos. I took each of these steps naturally, in their own time, without a label slapped over them. It was only after using each for a while that I learned how to make them play well together.

The changes in our world are overwhelming. Merely tackling investing, or personal finance, or frugality are three challenges that can fill weekends, or years. Trying to understand climate change, currency alternatives, political movements, and what to have for dinner can be too much to add on top.

I approach a lot of the changes simply, with an awareness of trends based on curiosity, but without adherence to external labels and other’s agendas. After a while, various choices based on my own values coalesce into something that maybe, sort of, possibly could look like someone else’s movement. Despite having some aspects of a stubborn streak, some external pressures will inevitably influence my life. As long as they align with my values, fine.

In class, we’ll talk about social media, but I’ll spend most of the time demystifying the terms, simplifying usage, and finding how to make the sites fit the needs, rather than the needs fit the sites.

Along the way, I’ll may bring up reputation economies and how Klout could supersede Google and maybe even the dollar, and how social media is green (but not as green as it looks), and how political action and activism are enabled, and how being a little closer to the edge gives a better view. It’s all about paying attention to values, ignoring labels, and making choices. It’s simple.

July's Floating - from Twelve Months at Deception Pass

July’s Floating – from Twelve Months at Deception Pass

Posted in Uncategorized | Tagged , , , , , , , , , , , , , , , , , | Leave a comment

Discounted For Risk

What can I say about the tiny company that is MicroVision? I don’t know any more than any other non-insider, and the insiders shouldn’t be saying anything. Investing in stocks can be a powerful way to manage your money, but you’ve probably heard the caution, “With the potential rewards, come risks.” The less commonly heard insight is, “As the potential rewards increase, so does ignorance.” A lot of people want to know what’s going to happen to MVIS, just like a lot of people want to know what’s going on with any small, highly speculative stock. The speculations make for great conversations, but they make for a difficult investment strategy. Long Term Buy and Hold of small stocks test risk tolerance, patience, and objectivity – all in the hope of rewards.

MVIS is a story stock, because MicroVision is a story company. This is the obligatory paragraph that acts as the opening scene in any serial TV drama. For those just tuning in – I described MicroVision in a post in October 2011, called Micro Vision. For those who don’t like clicking on links, the short version is that MicroVision has a disruptive technology that can create the next generation of displays. Computers in the house were revolutionary, but worked from TV sets. Then came high-quality CRTs. Then thin screen LCDs. Now laptops, tablets, phones, and even watches have thin displays.

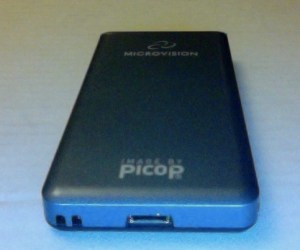
First Gen ShowWX (about the size of an iPhone - so maybe the next gen fits inside a watch?)

First Gen ShowWX (about the size of an iPhone – so maybe the next gen fits inside a watch?)

MicroVision has the technology that projects laser-sharp images that are always in focus, and can do so with less power, materials, size, and cost (we’re told) in packages so small that they can become as ubiquitous as the cameras embedded in those very same laptops tablets, phones and even watches. The previous posts dive into the technicalities and possibilities. Visit the discussion boards for more depth than I can provide. (The Motley Fool, Investor Village, Silicon Investor)

MicroVision has held such promise and claimed such possibilities for years. For about ten years, I’ve heard yearly estimates of their expected profitability – almost always about 9-18 months away. Supposedly, every day is progress towards that goal, but the stock has been on a bumpy downhill ride since the bursting of the Internet bubble. The downside has been a lot of losses for shareholders who’ve had to sell. The upside has been cheaper entry points for people who can buy. For the price of a pair of skis and boots someone can, in one purchase, accumulate a position larger than the one I’ve acquired from over a decade of acquisitions (which has a total cost equivalent to a very nice car.) The price has decreased while the potential value has remained roughly the same, which means the potential reward continues to grow.

Unfortunately, the logic that suggests buying very low now is barely changed from the logic that suggested buying seemingly low in 2005. We as shareholders can see the price, and can estimate the company’s present value based on a discounted future revenue. The logic and the math have suggested buy, yet the reality has yet to reveal a real reward. Ah, but now success should be so near and the price so low that the risk is minimized. Maybe. I don’t know.

One of the problems with buying stock in small startups is that they have no history of product revenues for a credible analysis. They do produce financial data, as every corporation must, but the reported revenues and expenses mean little when trying to assess the potential of the mature company and its resultant stock price. Small startups tend to work in secrecy for competitive reasons, because they are restricted by partner and customer agreements, to preserve reputations and careers, and because frequently there is little to say.

We as humans don’t like unknowns. Unknowns are verbal vacuums that we fill with stories. Shareholders know that no secret is perfectly secure; so, without quantitative reports, we dive into news from suppliers, we parse press releases, we dissect videos and other companies’ conference calls, and try to develop a picture that isn’t being officially revealed. It can sound like a foolish game, yet that game is precisely what the larger institutions are doing with teams of researchers and analysts.

So, why invest in something with such great unknowns while competing against teams of professionals? Because we investors in small companies aren’t necessarily competing against teams of professionals. The firms that are too big to fail spend little if any time with companies too small to bother with. Big institutions with big accounts want to invest in big companies because it is easier. If they need to invest $1,000,000,000 they have to research, analyze, and completely buy about 30 companies the size of MicroVision; or, they could buy a slice of a mega-corp in much less time and have much less risk. The mega-corp’s stock may not go up as much, but they’re less likely to lose their jobs if it drops.

In any competition, find your advantage that matches up against the other’s disadvantage. Individual investors buying stocks in well-known companies are competing on the territory owned by the institutions. That’s one reason I invest in small companies, but only in small companies that can potentially become big companies. I buy stocks that may be ignored now, but that can’t be ignored if the company succeeds.

Until the last couple of years it has been a strategy that served me well. (Want data? It’s in my book.) Dream. Invest. Live. As others who have analyzed my portfolio have noted, my stocks were hit by a perfect storm of bad luck. I think my portfolio’s performance has also been exacerbated by the current money flows within the market. The Fed’s quantitative easing and the disordinate accumulation of wealth has meant large piles of money are hunting for large havens. As a result, the market cap driven indices are setting records while many stocks languish.

At some point, the money that’s trying to get higher returns will have to look for alternatives. The money should flow back to the small startups. But there’s no guarantee. Maybe all of those investors will convince all of those companies to produce handsome dividends; and investing in small companies will fade, in which case, so will innovation.

I can’t say that at some point MicroVision will succeed. The discussion boards and private correspondence suggest that I am not the only shareholder who interpreted management’s comments as signs of success in 2013 (or 2012, or 2011, or 2010). We’re running out of year. Since the recent conference call, the private communications have increased, frequently including a dichotomy: re-analysis confirming potential rewards, versus an emotional awareness that the company, through competitive pressures, technical hurdles, or poor decisions may never succeed.

I can say that the daily fluctuations in the stock price of such a small company can look large and significant when measured against its pre-success value, but are small and meaningless when measured against the future value of its mature, successful self. I’ve seen it happen. I enjoy the speculations in words and investments (despite the current financial pain), but I know that the only thing to truly react to will be quantitative positive news and the consequential stock price move. Then, when it is a stock the institutions absolutely must have, I’ll be much more agreeable to taking enough of their money for some of my shares. Their unwillingness to take risk and encourage innovation will mean that their rewards will be discounted.

Or, the stock they overlooked will vanish, never to be looked at again; and their cautions will be justified.

I wish I knew.

Posted in Uncategorized | Tagged , , , , , , , , , , , , , , , , | 1 Comment

A Believe It Or Not Party

Thanks to everyone who showed up for the party. The dancing was memorable, as always. It was “A Believe It Or Not Party”, held because waiting for a big reason to celebrate was taking too long. Life shouldn’t be held captive by circumstance.

I enjoy parties, particularly giving them. They’re a great way to visit lots of friends all at once, get in some dancing, and end up with some tasty leftovers. (Thanks so much for the gluten-free pumpkin bread.) And I don’t even have to drive.

Articles describing how to decorate the house, what to cook, even how to invite guests are foreign to me. Over the years my parties have developed around some simple rules.

  • I’ll provide some munchies and some wine.
  • People are welcome to bring whatever they want to eat and drink, which is the easiest way to make sure there’s something that fits their taste and diet.
  • They are welcome to invite others because I will forget someone that should’ve been invited.
  • Kids are okay too, but guests have to leave with as many kids as they brought.
  • Folks are definitely encouraged to bring music and something to play it on. The more music and sound systems, the better the dancing, if it happens.

My house is only 860 square feet, and with the spontaneous help of those who showed up, we’ve had dance parties of thirty people with three different types of music. Living room = swing. Back room = blues. Carport = latin. And yes, last night’s weather was a few degrees above freezing, with wind, and rain – and salsa outside in November sounds silly until you realize that you’re warm by the second song.

Sometimes the dancing doesn’t happen because the conversations are so engaging.

I have fascinating friends. I invite a lot of them, but always a somewhat different set; not through any grand plan but because I trust them to fill in with invites to their friends, which leads to a bigger and different circle every time. For those who don’t know me, I am an extreme independent moderate. I am passionate about what people have in common and try not to make assumptions about affiliations and associations. One conversation was about opposing the legalization of marijuana (though marijuana is legal in Washington), while at the other end of the room people were comparing prices and describing the anti-anxiety benefits of partaking of the herb. More than two sides of the gun conversation were represented, and yes it is not an either or issue. There were liberals, conservatives, and innovatives. There was a great supply of corporate stories, the modern day fountain of clashing archetypes. And the circles shifted such that people from opposite sides of one issue were on the same side of another. No TV show is ever better than that. (Though I must admit that Aaron Sorkin gets close.)

Sometimes all of the conversation evaporates within minutes when a critical mass of dancing kicks in, people move the furniture, and we crank the volume. Having light furniture and being surrounded by vacant lots and empty vacation houses has its advantages.

If I’d described it as a frugal party it wouldn’t have been as appealing, yet frugal it was. The most valuable and precious elements are always the people. It cost less than some people spent on dinner out. The biggest cost was probably time, and the house needed cleaning anyway.

Everyone there had a reason not to be there, but they showed up anyway. It is too easy to step back from socializing when in the midst of turmoil and drama, or even just wind and rain. I stepped away from having parties for the last year or so, and after seeing the bill (which someone else surprised me by graciously picking up most of) I realized that I could’ve held a party or two during the hiatus.

We all have reason to worry, to step away while we sort through our troubles, or just to re-energize. Faking a smile may work for some, but an honest expression is worth more and is healthier. But stepping away too long is too wrong.
“Shared pain is lessened; shared joy, increased.” – Spider Robinson
We all have reason to worry, but we all have reason to share, and that is equally true of celebrations. I’ve waited for news to celebrate that was either getting an affordable mortgage or selling the house, having my portfolio sufficiently recover, making enough money without spending too much time, or even celebrating a serendipity that I have yet to experience. I’m glad I didn’t wait longer.

The party may be my last in that house. It may be the first in the resurgent series. I can’t know and must continue to live my life day by day, and sometimes hour by hour.

One intrepid fellow, and fellow MVIS shareholder, dropped by, commiserated a bit, weighed the crowd’s reaction to MicroVision’s promise (including the reaction of an ex-MVIS shareholder), mingled as well, and left me with a bottle of scotch from a city I walked through when I crossed Scotland. We may not have much to celebrate regarding MVIS, unless it ends up being buying at a record low, but we left the evening with the idea that celebrations can grow because good news can happen. Imagine the dancing at that party. We’ll probably have to buy a case.

Kirkintilloch, Scotland

Kirkintilloch, Scotland

Posted in Uncategorized | Tagged , , , , , , , , , , , , , , | 3 Comments

Value Planning

Plan for the future? Sure. Lately, I’ve been planning for the next hour or day. Planning for my far future, like next year, only happens if I want to get a headache. Long term life plans for coming decades are important, but they are extrapolations that must be made from a stable present. Right now, the best stability I can find is internal and doesn’t involve numbers but it does involve math. Me understanding me and managing me is a priceless exercise that costs nothing but time and courage. A sense of humor helps.

Retirement planning for the average person leading a normal life usually involves adding income, subtracting expenses, guessing at raises and inflation, putting in a safety margin, and extrapolating to some guessed at lifespan. Let’s see.

  • Median household income in the US ~ $51,000.
  • Median household net worth in the US ~ $69,000. (A figure which, ironically, ignores the value of the household’s house.)
  • Median age in the US ~ 37
  • Median life expectancy ~ 79

So, we just throw all of those numbers into a retirement calculator and what do we get? Nothing very useful. A person with the median income probably doesn’t have the median net worth, isn’t the median age, and doesn’t have the median life expectancy.

Personally, my income and net worth are far below the median while my age is significantly above it. As for my life expectancy, well, skip the statistics. At my age, lifestyle probably has a greater effect than my age on determining my life expectancy.

Several times I’ve calculated retirement plans, set that course, and embarked. Oh well. Calculating such a plan now would be meaningless. As so many people I know, extrapolating from where I am produces an answer of working for the rest of my life by necessity. That can be fun, if it is the right job in the right place with the right people. It happens, and I am glad I am closer than most to that model. Being closer to that ideal also explains a bit of my current financial deficit. Compromises happen. If I’d stayed in my engineering job, I’d probably be a millionaire – and possibly either crazy or dead from stress. My finances would’ve looked great, but my life expectancy would’ve been compromised.

Yet I am optimistic. How’d that happen? Am I just fooling myself?

I am optimistic because, for most people, life isn’t all bad luck. I had a string of it, but I can also have a string of equally good luck. If I only trusted to luck I’d be working without worrying about tracking hours or maximizing income. I’d be reading more books, volunteering more, and spending a lot more time hiking, skiing, bicycling, dancing, and generally socializing. Maybe that would be a better plan. Maybe that would more readily lead to serendipitous opportunities. There’s no way to know.

What I understand about my personal finances is amplified by what I know about me. I know that my needs can be easily met. My wants don’t cost much more. Frugality has its value. I’ve already found a place where I can enjoy life.

a short walk from my front door

a short walk from my front door

I have a wonderful network of friends. I have enough skills that I can’t exercise them all in a day, and that is a wealth for a lifetime. Many of them are even valuable enough to command a much higher income. Someday I may get the opportunity to enjoy that combination.

Because I need so little to enjoy life, it won’t take much for me to make more than enough. I’ll be able to follow one of my favorite old-school rules: Spend less than I make. Then, after I have cleared old, outstanding bills, I’ll be able to follow another of my old-school rules: Invest the rest. If I am spending less than I make and investing the rest, and doing so in ways that are healthy, then I can sustain a comfortable life. That retirement plan doesn’t fit into a calculator, and it doesn’t need to. Check out my book (or buy it). Dream. Invest. Live. Those rules are in there, and there isn’t a retirement calculator.

Of course, I look forward to making a lot more than I need, benefiting from successful investments, and being comfortably comfortable. And I also buy lottery tickets. Why pass up an opportunity and a chance to dream?

My Rule of 7 and Retiring One Percent both get about as detailed as I think is necessary for retirement planning for those of us without those median jobs and lifestyles. New Road Map’s Nine Step ProgramNRM logo is a good example of planning that isn’t only a retirement plan. Life is uncertain. Pretending that it isn’t is appealing, but it is also an illusion. I’ve had enough retirement plans fade for me to think otherwise. Personal understanding, living according to simple values, and persistence are more in my control, have as much certainty as I can give them, and are far more valuable. That’s my plan – at least for now.

Posted in Uncategorized | Tagged , , , , , , , , , , , , , , , , , , , , | Leave a comment

Wealth Through Health

Yes, it is possible to hear good news from the biotech community. The problem is understanding what they say, why they’re saying it, and what they’re not saying. Geron (GERN) had some great news. Pardon me as I look up imetelstat and myelofibrosis, and add them to telomerase. Even if I know what they mean, I have to remember how to spell them. That simple dictionary act is enough to thwart legions of investors. A couple of decades ago I realized that such simple acts reveal an advantage that individual investors have over the institutions. Simple, but not too simple, is powerful – and reaches beyond stocks.

Geron is a bold company. They find the big medical problems that others are trying to treat with slight extrapolations of existing treatments, and decide to develop fundamentally different solutions. They attempt to skip the toxic cocktails and instead develop more systemic treatments. The drug that raised the stock was Imetelstat, a drug that inhibits the production of telomerase, and hopefully treats a blood disorder called myelofibrosis. Using smaller words takes more sentences, but it also leads to the reason for optimism. Geron is trying to take advantage of the fact that many cancers have the same thing in common: misbehaving cells. The cells don’t die the way they should. Geron and others hypothesize that is because the molecule that acts as a countdown timer, telomerase, doesn’t do its job right. Manage that molecule and manage the illness. The news suggested encouraging results for a blood disorder treatment. That’s great. What’s even more appealing is that, if this technique works for this disorder, it might work for others too. That’s why GERN has always been a high-visibility stock. They are very risky, but if they succeed they may succeed spectacularly. They’ve also tested my patience because I’ve held them for over 10 years (and sadly I sold half my position a few months ago because I had to.)

So, why doesn’t everyone jump up and cheer and rocket the stock? Because biotech is risky, the results are hard to interpret, the trials are expensive and take a long time, what works for a few patients may not uncover side effects within the larger patient population, and even if all that works the company has to clear the hurdles of FDA approval and successfully marketing the treatment. But maybe they’ll succeed.

But surely, if a revolutionary treatment succeeds far better than the competition it is bound to succeed financially, right? Nope.

Dendreon has been called, “the largest marketing failure of the most successful company“. If Geron uses leading edge technology, Dendreon is at least close enough to peek over the edge. Dendreon developed a cancer vaccine. That’s sounds simple, but think of it. Compare a vaccine to chemo and radiation. Dendreon managed to develop a treatment that helped the body combat its cancer with its own immune system. The side effects of chemo and radiation are enough to scare away patients. Dendreon’s treatment, Provenge, is like getting the flu for three days, maybe. Each treatment was very expensive, but the total cost was much lower than chemo and radiation, was simpler to administer, and led to a better quality of life than other treatments. I was glad that I’d done my research, bought early and often, and had a giddy and heady ride as the stock climbed from under $3 to over $50, and looked like it would rise into the hundreds. Friday it was trading at under $3. Whether through poor marketing, bad management, or intense counter pressure from the entrenched industry, the company and the stock have not succeed – even while Provenge has been proving itself in practice, and proving the technology may also work in other cancers too. Sadly, my dream of having a large enough portfolio to launch into philanthropy was undermined as I had to sell my stock at ever-decreasing prices. When the last of my DNDN was gone, so was my history of paying my bills on time.

Biotechs spend billions of dollars trying to improve patients’ lives. Multi-phased double-blind clinical trials, peer-reviewed, government-regulated result in bizarre mixes of compassion, finance, bureaucracy, and public perception. That’s why Geron’s news really hasn’t actually been released yet. The news won’t be delivered until December at some conference, yet the speculation begins based on snippets of abstracts.

As much as I am an advocate of innovation, I am also an advocate of simplicity and resourcefulness.

I live on an island that prides itself on its organic farms, fresh seafood, and a clean environment. Even the bicycle community here has an Occupy theme. (Occupy Your Bike!) There are so many health and food advocates around here that bringing a dish to a potluck requires an ingredients list so folks can check against diet restrictions and preferences: gluten or no, vegan or no, dairy or no, seafood or no, GMO or no. We get the chance to eat in whatever healthy fashion we prefer. (I know even know a good source for paleo granola.) Primal Island Every diet has its advocates, and while they frequently are mutually exclusive, this is a place to learn a lot about each – and witness the effects in the health of the people.

Maintenance is cheaper and more effective than repair or replacement. Living healthy takes a bit of thought at the start, but it leads to less time spent on sick leave or managing the side effects of persistent medications. Want to bring down health care costs? Eat right. Exercise often (wearing appropriate safety equipment of course). Rest, relax, and enjoy. (So says the guy who knows he’s working too many hours, but that’s another story.)

See, that’s so simple it takes fewer words and syllables to describe.

Yet, I wonder. We spend billions systematically trying to cure our ills. How much more effective would it be to systematically find ways to eat and live healthier? Where’s the billion dollar clinical trial study that demonstrates the effect of eating tomatoes, garlic, olive oil, mushrooms, heritage wheat, and raw milk cheese? Wouldn’t it be great and grand to find that our government had proven that a mushroom and cheese pizza would keep down our health care costs?

Dinner tonight was fried rice with curried chicken. All of the veggies came from my friend’s garden. We bought the chicken and rice, both organic of course, and I enjoyed it with a nice glass of white wine. I won’t be able to prove its health benefits, because evidently the lack of a disease is not an sufficient enticement in today’s society. But maybe some day it will.

It’s late enough now that it’s time for popcorn, and a relaxing in front of a movie at the end of the day. I hope Geron, GERN, the shareholders, and most importantly the patients succeed. Simple of complex, the celebration will be welcome.

Posted in Uncategorized | Tagged , , , , , , , , , , , , , , , , , , , | 2 Comments

Poverty Recovery Retirement

Celebrate! This is worth much more than a cupcake. Today I wrote myself a check. The check was the largest I’ve ever written from my business to me. Maybe, maybe, I can convince the mortgage company to renegotiate my mortgage rather than foreclose. Maybe, regardless what they do, I’ll become one more story of recovery. Despite conventional wisdom, stereotypical patterns, and ideological promises, there are no guarantees. There is, however, considerable and very welcome hope.

Regular readers skip ahead, but for those tuning in late, the last two years of personal financial implosion nearly eradicated my savings, have left me in threat of foreclosure, and have left me with a great imbalance where work overwhelmed life without the commensurate compensation. Triple Whammies, Backup Plans, and decades of practiced frugality have been my drama, effort, and style as my net worth dropped by more than 95% while my income has been building from almost nothing to maybe enough. (Need a consultant who understands the ride from not much to millionaire to not much to who knows where next? Give me a call.) Just in time, my two largest clients (HCLE and NRM) agreed to more than double my time, earning me enough to buy hope and maybe more.

Okay, regular readers, re-engage.

Experienced entrepreneurs, I have some lessons to learn from you; particularly, how you pay yourself and the government, and how you’ve managed to get through tough times. (Got a blog? Add the link to the Comments section so others may learn too.) Self-employment involves an internal wage negotiation between employee and employer. How much can the business really afford to pay? Folks in the bank lobby may have heard the logic gears whirring in my head as I stood at the counter trying to decide on a number. I hope I picked right. Too much and my business can’t sustain it. Too little and my pay can’t sustain my mortgage and the rest of my bills. The only true test is experience. Stay tuned. The next few months will tell a tale.

I’ve bounced along the poverty line, staying above it, but seeing it on a regular basis. Until 2013, I stayed clear by selling my investments. Want to see my historical returns? They’re in my book, Dream. Invest. Live. Dream. Invest. Live. Unfortunately, when the investments were nearly gone I had to make the painful decision to quit paying my mortgage. The mortgage company wasn’t happy about that.

The mortgage company wasn’t happy about my lack of payment (not a surprise considering that I wasn’t happy about not paying either), but the reality of how many other people were in similar situations sunk in when I witnessed how practiced the debt collectors were at attempting to extract payments. The industry’s annual revenues are more than $10,000,000,000. In general, creditors are due their money, but so much money is involved in trying to reclaim the arrears that I suspect the incentives are skewed. If all of the debts were forgiven, how many debt collectors would be unemployed?

Poverty is defined by money, and money carries taboos, so most conversations avoid discussing poverty, or only discuss it as an abstraction. Oh yes, we must do something about that. But don’t give that homeless person a handout.

The surprising thing is how many people experience poverty, and how many get out of it.
“So while 38.9 percent of Americans will live at least year under the official poverty line between ages 25 and 60, just 11.6 percent will spend five years or more impoverished.” – The Atlantic
In my opinion, even 11.6% is too high a number for a developed nation because what have we been developing if that many are in that much distress?

The positive side is the 27.3% that get themselves out of poverty. We are a hard-working people, regardless of what the pundits say. Productivity continues to rise faster than wages. That wouldn’t happen with a population of slackers.

My personal recovery is redefining my life, though not my lifestyle. Frugal remained my style when I was working hard when young, retired early, or working hard at recovery as I near the border between middle-aged and aged. The major redefinition is retirement. Significant positive financial news is always possible (hello lottery tickets and MVIS), but retirement has returned to the realm of speculation rather than planning.

There again I am not alone. Within the multi-layered cultures that are my community, it is common for non-corporate folks in their fifties to be telling tales of expecting to work as long as they live. Necessity, not choice, drives their expectations.

Too many of them have been told that, for their situation, they’ll need more than a million dollars to retire. Many are aiming for such a figure. Maybe that number is correct, based on a given set of assumptions. Sadly, the reality check is that only 13.5% of households have net worths of more than $500,000. Net Worth and Asset Ownership of Households- 2011 The borderline for the top 1% is about $8,400,000. Even if it only took $500,000 to retire, then about 86.5% of households can’t retire. If it really takes millions, then the real number of households that can retire is between 1% and 13.5%. Granted the numbers are skewed because many households represent younger people, but retirement is a financial criterion, not a chronological one.

The good news is that the greatest control any of us have on our lifestyle and chance for retirement is our own spending habits. Frugality, or even just ignoring most advertisements, is more powerful than how much is money is saved. A frugal lifestyle has provided me with stability when I needed it most, and is an amplifier on every earned dollar as I recover.

So, time to pour a glass of wine, stoke the fire, eat a bit of chocolate, and read a good book at the end of a very long day amidst an incredibly busy phase of life. Celebrate – because amongst the world’s turmoils, it is possible to exert just enough control to create fine moments.

Posted in Uncategorized | Tagged , , , , , , , , , , , , , , , , , , , , | 2 Comments

Dramastic

Isn’t the English language marvelous? It’s been said that it never turned away a word, so it arguably has the largest vocabulary of any common language. Besides, if Stephen Colbert can make up words, so can I. I made up a new word today: dramastic. On many levels, life has been dramatic and drastic, or at least has felt that way.

This morning the lights were flickering because of a storm, but the power stayed on (mostly); my workload is satisfyingly constant, and I’m adapting to the effort and the storm; and I’m preparing for the meeting with the mortgage renegotiation meeting, as cash flow improves but hasn’t been received and posted. The word arose during a breakfast conversation with a friend who is leading an equally dynamic life – who has been involuntarily sidelined because both arms are in slings after a bicycle accident. Believe it or not, adding caregiver to my daily schedule hasn’t been an insurmountable disruption. We had to laugh at our situation, and my tired mouth tumbled up two words into one. “Well, it’s not as if life has to be dramastic.” With everything going on, there’s no need for drama or drastic actions.

I look forward to writing the post that signifies a pivotal moment when everything turns right again. It happens in the movies, but this blog is about reality. I’ll continue buying lottery tickets though. Hey, it can happen. That would qualify as dramatic.

It is unfortunate, but sometimes difficulties must be addressed with drastic actions. Accidents or sudden bad luck frequently require immediate responses from people willing to trust to intuition and training for choosing actions that are hopefully good enough. Thank you, emergency responders (for whom we should find a shorter title that isn’t just rescuers.)

Today’s storm, my business, my mortgage, and even my friend’s healing all benefit from some quick action; but the effectiveness of the quick action is amplified by months or years of undramatic, undrastic actions. Houses are built to withstand storms, and are stocked for power outages. My business is improving because I’ve worked on it for years. My mortgage situation has been a year-long maneuvering around options and responses that have benefited from considerable internal deliberations. My friend’s broken arms are recovering more quickly than most because decades of healthy living, exercise, and attitude produced a body prepared to repair itself.

Personal finance is rarely improved with dramastic actions, though the ceremonial cutting up of credit cards can be a life-changing ritual for many. Personal finance can be so dull because it is best done in innumerable, small, considered steps. The daily fiscal exercise of becoming a little more aware of expenses, income, investing, and most importantly values can seem so trivial and daunting that most ignore it.

Replacing a vending machine’s potato chips with a baggie of chips from a party-sized bag at home is a small thing. Saving a dollar a day isn’t much compared to the tens of thousands most people make in a year. After a day or two, using a thermos of homebrew (I’m thinking coffee or tea, but hey, to their own brew) may be more satisfying and much cheaper than standing in line hoping barista will get your order right. Develop the habit of looking for a simpler way to do things and the challenge becomes its own hobby. Play with that hobby long enough and create a life no one else can match – because it is based on your values, not someone else’s. And it probably costs less and is more gratifying. Others may see the actions as drastic or dramatic, but from within they are simple and obvious.

Despite, or maybe because of, my experience in the stock market I am frequently asked if someone should buy stock. It is impossible for me to know the answer. Only that person can know; and, because they are asking the question, I suspect they don’t know either. Whether it is stocks or bonds or commodities it is possible without any dramastic action to find what works. I suggest buy a little, wait a few days, and check your feelings. If it doesn’t feel right, sell. The advantage of liquid assets is that they can be sold again. Unless you’re hit with extraordinary good or bad luck, the selling price a few days later will be close to the buying price. Keep the cost of commissions down and you may have spent less than the price of a meal, and much less than the price of a counselor session. You may have even made some money. If buying feels right, good, but don’t take that as a reason to jump in with everything. That would be dramastic. Step and learn and check and decide what your next step will be. You may miss opportunities, but it is more important that you learn what and why you are doing what you’re doing. (And check my Triple Whammy again to see what can happen.)

I look forward to a positive and dramatic moment that returns me to financial comfort. In addition to state lotteries, many of my stocks are effectively lottery tickets. MVIS hitting $1,500 would be a 1,000 fold increase over Friday’s closing price of $1.50. Sounds incredible and I’m impressed with how many individual investors think it is possible.

I look forward to a positive and dramatic moment that returns our society to one that lives by the Golden Rule. It could happen. But many thought the dramatic rise of Barack Obama would create such a change. And yet, well, there’s evidently a lot of work to do.

Today’s storm is mostly gone. A short hail storm was probably the last episode in today’s event. As dramatic as it was, the only drastic action was to run to the windows and watch pellets bounce off the roof. The ice is melting. I think I’ll stir the fire, maybe throw on a log that I brought in earlier, and then put all of these concerns aside. I’m going dancing. I looked silly when I started, but evidently lots of playful practice has resulted in a reasonably full dance card. Nothing dramastic required.

Posted in Uncategorized | Tagged , , , , , , , , , , , , , , , , , | Leave a comment