Off The Market

See anything different? DSCN5128 The For Sale sign is gone. My house, my home, is off the market – for at least a while. Welcome to yet another episode in “Maybe I Get To Keep My House”. After two years of trying to sell it, I decided to take my house off the market just as a possible mortgage modification is coming through, and as the local real estate market makes agents busier than they’ve been for years. Things change. Things stay the same. What’s news about that?

  • In the summer of 2011 my finances were hit with a Triple Whammy. But hey, I’m an optimist. They’ll come back.
  • By spring of 2012 my finances hadn’t come back, despite my optimism. If things didn’t improve quickly and significantly, I wouldn’t be able to pay the mortgage. Evidently, it was time to sell my house, my favorite home. I put it on the market at the same price I’d bought it for five years earlier.
  • In the fall of 2012 my finances hadn’t recovered. None of my Backup Plans were working at full force. I was paying the mortgage from my IRA, and my IRA was almost empty. I stopped paying my mortgage. The emotional pain was surprisingly intense. The Mortgage Company Tactics didn’t help.
  • In the spring of 2013 the mortgage company finally posted a Notice of Default on my door. The next step would be the all-too-common foreclosure notice. Ah, but there was a phone number on the notice. I’d had such bad experiences in previous communications, but this one promised to be with an independent third party, Parkview Services. Their advice steered me into a beneficial delay, and then mediation based on an intimate and experienced knowledge of the foreclosure and mortgage modification process that few homeowners could attain.
  • During the summer of 2013 a trusted friend and real estate agent who has seen me through several deals agreed to take over from the previous agent. Kath has seen me in the midst of intense stress before, and knows how to communicate with this somewhat-stubborn ex-engineer.
  • Through the summer and fall of mis-scheduled meetings we (the mortgager, Fannie Mae; the mortgage servicer; the mediator, my counselors at Parkview, and me) finally came up with a schedule for a possible mortgage modification.
  • Thank my two biggest clients (HCLE and NRM) who readily agreed to double my hours and give me a raise in the fall of 2013. My business income increased enough to at least pay rent, and maybe qualify for a modified mortgage.
  • Good news arrived in the late winter of 2014. I was offered an trial payment plan that would possibly qualify me for a modified mortgage. The payments are about the same as rent. Good.
  • Here we sit, spring of 2014. The real estate market boom finally crosses the moat from the mainland to the island. My agent friends are busy. The mortgage modification may be offered within the next few weeks. These are dynamic times.

To those of you who skipped past the bullets, I don’t blame you. The details of this history do not make for a simple story. We are comfortable with the simple and the quick. As this situation flows around me I’ve come to realize why less is said about the personal stories behind foreclosure. Take a look at that lineage. That is the simple version, and its latest episode includes a twist.

I took the house off the market because the amount I owe has risen every month that I haven’t paid the mortgage. Even the trial payments I am making do not necessarily keep the penalties from accumulating. As of April the amount that I owe probably couldn’t be covered by a full-price offer. A full price offer a couple of months ago may have left me with some money for the first, last, and deposit for a rental; but the market wasn’t active then. The market is so active now that I’ve had more showings in the last few weeks than I had in the previous year and a half; but selling now would possibly cost me thousands of dollars.

Such stories don’t play well in the press. They don’t fit into a 30 second sound bite. If you skipped the details you can appreciate the time constraints of a reporter trying to compile the best story in the shortest time. And as I said above, my story is simpler than most. A relatively healthy single guy with no dependents, only one mortgage, who lives frugally and responsibly, with advanced education in a key field, whose mortgage wasn’t underwater at the start because he put 20% down. Imagine how complicated such stories get with health issues, divorces, kids, second mortgages, and poor employment prospects. When the news gets complicated the press tends to report the stats rather than the stories.

It is good to get my home off the market. Of course I hope the mortgage modification comes in as suggested by the trial payments. There’s a lot I want to do with the house that only makes sense to tackle if I am going to be here for years. I still haven’t planted this year’s vegetable garden because I don’t know if I’ll be here to tend it.

But the sage and rosemary are doing well.

The sage and rosemary are doing well.

My house has only marginally been “staged” to appeal to potential buyers; but now I can pull the coat rack out of the closet, put the messier bits of a real kitchen back onto the counters, not worry about strangers having access to my personal stuff, only make the bed (er, futon) when I want, and maybe finally move the standing desk out to where there’s a good view (which happens to be beside the kitchen).

A few conversations with neighbors marked the difference between perception and reality. They both saw me as doing “really well now”, based on – what? I don’t know. We work from illusions. Graciously, each listened to my story, and I appreciate their listening. One couple shared their story too. They too were on the edge, but no one could tell from the way they act, the appearance of their home, or from what they’ve made known. The simple story that all is fine is a fine one to leave their neighbors with, except I guess for neighbors like me who sincerely and honestly answer questions that are usually avoided. Proprieties aside, people appreciate truth.

A dear friend asked where I thought I’d be in thirty years. That is the easy question to answer. I am an optimist. I expect to be in a much better place. I even hope to be somewhere better within the next three years. But the next three months, weeks, or days are less certain – which I guess is no change for any long-term optimist and short-term realist as myself. And possibly also the case for the quiet crowd living through similar circumstances. May you experience the change you wish to see. Now, that would be news.
Posted in Uncategorized | Tagged , , , , , , , , , , , | Leave a comment

You Are Not Your Job

A friend lost a job. How often have you heard that one? How often has it been their fault? Lately, losing a job means a corporation downsized, outsourced, or randomly re-organized. Decades ago losing a job probably meant doing something wrong. Now it means being in the wrong box on the organizational chart, or being on the wrong side of a line in some spreadsheet. Unfortunately, a lot of attitudes and perceptions are based on a society from decades ago. Now, young people are the wise ones because they know that careers are an illusion, every job is temporary, but who you are prevails. The trick is to make that nice sentiment mesh with commitments like thirty year mortgages. And yes, it can be done.

I can think of two or three people who have lost their jobs for personal reasons. Nothing that a bit of maturity won’t change. Learning to play well with others is tricky. Almost everyone else I know who has passed or is passing through unemployment was launched into that financial space because a company either ran out of money, or wanted to make a lot more regardless of the cost. The quick list includes vice-presidents of marketing, technical experts in artificial intelligence, programmers with multiple degrees, engineers from every field except petrochemical, linguists, healthcare professionals, information specialists, and at least a few ex-professionals so upset that they’ve become reclusive at the very time they have to step into uncomfortable change.

Corporations lobby Congress to allow more foreign workers to fill critical skill gaps at the same time that I can run into folks with such resumes just by walking into the local coffee shop. I sense a dysfunction that I can’t solve.

The ex-professionals who rebounded the quickest emphasized their expertise and re-created themselves as consultants. Their jobs may have been taken away, but their skills stayed with them. Self-employment requires a new set of skills, but it comes with a large dose of freedom. Take a severance package, if you’re lucky. Take a month or two off because the last few months or years were probably in a stressful position, and then fix up the resume (and the LinkedIn profile) and get in touch with the network that was developed over years.

The ex-professionals who have the most fun are the ones that, with the time to look at their finances, realize that they could retire. It is easy to get so wrapped up in work that a house and a portfolio have quietly grown to more than enough. Yes, you can take money out of your IRA while you are young. The best way to find out is to try, and be willing to change back if necessary.

The ex-professionals who grow the most are the ones who, through choice or necessity, find within their self more skills and talents than their job ever let them develop. Either through entrepreneurship or non-profit participation, there are plenty of ways to grow that have nothing to do with corporate America, and they can pay nicely in both money and satisfaction.

I was an Aerodynamics Stability & Control engineer (don’t worry about what that means), but I was also good at a lot of things that weren’t included in the title: program management, strategic planning, team facilitation, presentations, cross-team coordination, etc. (Check my bio for a long list.) Each was enjoyable for different reasons. And yes, I actually enjoy program management and the rest. Go figure. But then I also learned that I was reasonably good at writing, photography, teaching, and public speaking. I was more than my job title. I am more than any label slapped on me, though I do rather like the title of Renaissance Man.

As people live longer we are redefining retirement. Even assuming a career that lasts until Social Security kicks in, an idea that is foreign to many, when retirement arrives it is necessary to redefine your role. The money is important, but personal values eclipse finance. That can seem like a blithe statement, but losing the identity associated with a job is the best time to concentrate on what should never be lost, a person’s morals and ethics.

Let’s not oversimplify things though. As much as personal finance should be about the person, finances happen. I’m very aware of how money flows can direct a life. I’m also aware of how hard it can be to find a corporate job. (My Jobs Report) That’s the reason for action and backup plans.

As I’ve said before, I’m asked how I’ve managed to stay positive throughout my turmoil.

  • One, I haven’t done a video of my head-banging sessions.
  • Two, I know that a bit of complaining is necessary, but that things will get better quicker if I concentrate on the better parts of my life.
  • Three, I’ve recognized that much of what I am going through has less to do with me than it is does with dysfunctions in the system. And
  • Four, I have learned better and deeper than ever what my true values are, old attitudes that really didn’t matter, and what I won’t compromise regardless of money.

The world of my first mortgage was very different. I’d be within four years of paying it off. ARPAnet was being replaced with the Internet, but hardly anyone knew it. The fears of climate change were being debated but they were overshadowed by the threat of Mutually Assured Destruction. Stocks were still traded between people instead of computers. And careers were what people aspired to. Retirement plans were simply assumed.

A lot has changed. Personal values haven’t. For anyone working at that time, decades of training and experience have developed impressive skills, talents, and wisdom. The world still needs such people. Corporations may dismiss them in batches; but ventures, philanthropies, charities, and personal passions can benefit from incredible people. Redefine yourself and give them the chance to benefit from you, and you from them.

PS It looks like another round of job shuffling is in action. If you another outlet for your story I can include you in my Find A Friend A Job posts (#FAFAJ). Another valuable thing no one can take away is the support we give each other.

Posted in Help Find A Friend A Job, Uncategorized | Tagged , , , , , , , , , , , , , , , , , , , , | Leave a comment

Ruts Routines Revolutions

April 20th, a fine day for a party. A fine day to celebrate the break from tradition that was the beginning of the Revolutionary War. Most folks thought April 20th, 2014 was Easter. Well, yes; but someone had to spend time “paying homage to this nation’s radical dissident forebears”. Friends held a party. I had to go. One of my ancestors signed the Declaration of Independence, that radical. Breaking from traditions has been a recurring theme, recently. That’s okay. As Thomas Jefferson said, “I hold it, that a little rebellion, now and then, is a good thing, and as necessary in the political world as storms in the physical.” Occasionally stepping into and then breaking out from traditions, ruts, and routines is healthy.

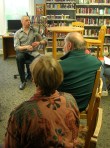
Thursday night I gave a talk at a local library. The Friends of Langley Library hosted my talk about my most recent book Walking Thinking Drinking Across ScotlandWalking Thinking Drinking Across Scotland. They’re a brave bunch because I rarely know what I am going to say. To me, what the audience wants to hear is more important than what I want to say, though I make sure I slip that in too. Evidently I do it well enough because they’ve asked me back for next month too. (I’ll talk about the year-round wilderness that is the Washington Cascade Mountains.)merritt cover

Usually I start before the introductions by chatting with the early folks about their stories. No need to repeat things they know. Good to know the hooks that allow me to spin off from their comfort zones. This time we broke with tradition by including traditional music. Bagpiper Don started the evening by playing the small pipes (and who is also entrepreneurially embarking on non-traditional ways of making income, like making and selling biscotti.)DSCN5097 His playing took me out of my comfort zone, but entertained the audience which was more important. The change in routine fit in nicely with the opening passage that I read from the book, and was a reminder that I should be willing to change.

We build ruts. We build them out of habits and for a purpose, even if we don’t realize it. Our ruts keep us in the vicinity of what we think we need and aim us towards a goal we expect to reach. A rut is a person’s self-built one-dimensional maze that includes walls and a picture of cheese. If it is a deep enough rut the horizon becomes the top of the trench that we can’t see over. The world shrinks to something that seems controllable where everything except the end is within reach. We humans are very good at putting ourselves into silly situations.” – Tom Trimbath

Lately I’ve been in a rut that I’ve consciously built to make enough money to keep my house and pay my bills. Stay tuned. The next few weeks will tell whether I’ve satisfied the mortgage servicer. In the process of working within that very productive rut I’ve witnessed the distancing that happens with everything outside of it. Personal traditions of how I rested and recreated are obviously removed. I’m willing to stay within this rut because I am aware that it is temporary and also because I have no other obvious rut to switch to. The goal nears and then change will happen.

In the last row at the talk was a woman who left early. I didn’t take it personally. Free talks carry no commitment and with so much to do on Whidbey I expect about 20% of the audience will arrive late and 20% will leave early. It turns out that she is challenging her lifestyle as well. What I call ruts she calls routines. While I’ve broken out of mine by bicycling across America or walking across Scotland, she’s breaking out by traveling the world one place and month at a time. Every month will be a mix of old traditions that tag along, new ones from the place she’s moved to, and an inevitable blend that will help redefine her life. Her story is just beginning, and she’s chronicling it. Tune in.

There are a lot of people who feel that they are in ruts that they didn’t choose, ruts imposed on them. Or maybe they chose that rut, but it was a choice from a selection of one, all others being illegal, immoral, or improbable. While many people are cheering a recovering economy, I know too many people who wonder how their job or business will ever lead to anything better than what they know now. Quite a few conversations end with jokes about the lottery, MVIS (which may be the same thing), or apocalypses that are personally positive. If the currency markets crash a struggling farmer or excellent is suddenly the richest person in the neighborhood – and if you know how to brew beer, congratulations.

Local unconventionally traditional eggs - not sorted by size or color

Local unconventionally traditional eggs – not sorted by size or color

It can get dark in those ruts and a friend asked me how I manage to pump sunshine into mine. Looks can be deceiving, and yet, maybe my attitude means my rut is better lit than most. Pardon me as I reach for the light switch.

In America we underplay the role of luck. If you are successful, you get all the credit; and the few that are wise humbly acknowledge the contributions of others. The sad part is that policy and perceptions are driven by the corollary. If you aren’t successful, then it must also be your fault.

Effort and luck both contribute to a person’s life path. Where and when you were born matters. Hard work improves your chances generally, unless you’re working on the “wrong” thing. Jobs openings aren’t filled by every hardworking applicant; but are filled by one applicant who is probably hardworking and who possibly stood out from some lucky connection they made with the employer. The rest of the hardworking applicants have to work hard at applying again, and possibly eventually turning to entrepreneurship (check out Ideaworth’s blog).

The extremes are easy to talk about because their lives make good stories, and we enjoy good stories even if they are dramas instead of comedies. Some people seem to sail through life trusting merely to luck, or to mentally manifesting their future. Others work every day and struggle to the end. But there are also those who mentally manifest a fantastic future – right up to an unfulfilled end. While others may work hard, and find they picked just the right job at the right time despite bad luck.

My optimism reaches in by reminding me that, even while my life feels like an extreme, almost every life includes a mix of effort and luck. Persistence is the great enabler. As long as I persist, and as long as I remain aware of other possible routines, I know that in general that combination of effort and luck will prevail.

Look at the American Revolution. A baker’s dozen of colonies that were much too young, small, and poor stepped out of ruts established over centuries. Despite a string of defeats that should have led to unconditional surrender and retributions, they persisted through effort and luck – (and the French, but it isn’t fashionable to point that out.)

Look around at your ruts and routines. They may serve you well, but it may also be time for a little revolution.

Posted in Uncategorized | Tagged , , , , , , , , , , , , , , , , , , , , , , , , , | Leave a comment

Utopia Yourtopia Mytopia

I am glad to see that utopia is still more commonly used than dystopia. (Check Google Ngrams and Google Trends for data.) That alone means there’s hope for the human race. But, except for magazines like Yes! and Intelligent Optimist, there’s also a lot more discussion about financial, environmental, and societal disasters. It seems that we are far from utopia. That’s also nothing new. One thing that is always new and unique is every individual’s image of utopia, their mytopia or yourtupia. No matter what the world is going through, understanding mytopia is one of my best guides to living.

The desire for utopia has always existed. We want to be and do our best, and we want a world that lets that happen. Many now see utopia as eco-friendly, peaceful, and thriving with clean cities, ample resources, and a sustainable civilization. I suspect the cavemen utopia was a clean cave, easy food, a happy clan, and not being eaten by some fanged beast. Same thing, but it looked very different.

We do seem to emphasize the downside. While there are extreme positivists, much of human communication is about what bothers us. The media feeds on our tendency. I know that I am guilty of it as well as I give a personal voice to troubles that are usually reported in generalities and statistics. I’m known for being positive and optimistic, but I’m also known for pointing out dysfunctions and incongruities. That’s reality.

Human nature plays out a bit in this blog’s traffic. The most popular post is about one man’s contribution to community, A Bow To Drewslist; but followup posts languish. Solid traffic comes to my less-than-positive posts about health care, mortgages, and financial turmoil; some people stop following, but those that follow follow methodically and gather audiences of compatriots. (They are also the first to hear the good news and appreciate the contrast.) The greatest volume of reliable traffic is for any post about stocks and investing; which, I guess, is because so many bloggers write about investing merely as a sales pitch for their services. (I’m happy to help clients and sell books,Dream. Invest. Live. but the numbers prove that I write this blog largely without financial compensation.)

The classics prove the appeal of the dismal. What’s more dismal than Hell? Yet, Dante’s Inferno is recognized by many who’ve never read any of the classics. The story is terrible and rich. Most people aren’t aware that Inferno is the first book in a trilogy (oddly named the Divine Comedy, so there are definitions that were broader back then.) The second and third books are Purgatorio and Paradiso. Dante’s journey didn’t end with an escape from Hell. He went through Purgatory and Paradise. If we were so in love with utopia, Paradiso would be the best seller, not Inferno. But in each subsequent step away from Hell, the verbiage becomes less vivid and less engaging.

Society and individuals progress regardless of our apparent concentration on destruction. We talk about how bad the weather is, and we build stout buildings – though they aren’t as stout as a cave. We complain about finances, and generations continue to work hard hoping to get ahead. We shout about injustices that never seem to fade, and yet progress is made over decades.

Regular readers are very aware of my turmoil of the last few years. Readers from the beginning can see the contrast to the days of dreams that were almost realized. (Until the dreaded Triple Whammy.) Through it all I have aimed at a dream, a mytopia, that has changed little except for the necessary change in scope and timing based on finances. Mytopia may be further away than ever, yet it draws me more strongly because each setback required me to reevaluate my values and expectations. The biggest jump was realizing that the standard American dream wasn’t just a bad fit, it was counter to what I wanted and valued. Everything after that has been an intensely personal refinement.

Mytopia is a small house; on sufficient land for comfortable autonomy; in a sustainable region, environment, and community; with enough resources to live with ease. There are plenty of other details, some of which are so personal I won’t share here; but, most of them can be summarized as Live Long and Prosper, Relax and Enjoy, Be Excellent to Each Other, with a good chance to practice DFTBA (the catchphrase of vlogbrothers, Don’t Forget To Be Awesome.) It is not a small life. It is a life that is just the right size to meet my abilities, needs, wants, and resources. – and help others.

What I have to keep in mind is that utopia is an abstraction, and becomes an easy way to say no to possible solutions. My current house is my favorite home, and yet it is obvious that it is a little too big (even though it is only 840 square feet), on a lot that is a little too small (because 7,000 square feet aren’t enough for a proper garden plus outbuildings plus workout space plus etc.), in a neighborhood that doesn’t encourage decentralized utilities (except for the house-by-house septic systems, which I want to replace with a proper composting toilet.) Mytopia is for something else, which would make it easy to give up what I have, but what I have may be good enough. Most people on the planet would consider my house, its yard, and the utilities to be luxurious. And they are right. And I am right to acknowledge that something a little different could be a lot better.

The only true judge of such decisions is the person involved. Knowing that you are the only person that can truly judge you and your choices is powerful in housing, finance, and generally in how you want to live your life. Go ahead and complain because that emphasizes the contrast between where you are and where you want to be, but don’t let a search for utopia or yourtopia or mytopia pull you away from what is already good enough.

Relax and Enjoy

Relax and Enjoy

Posted in Uncategorized | Tagged , , , , , , , , , , , , , , , | Leave a comment

Personal Trust Diversification

Here’s my plan. It’s Saturday, the day I tend (with several long lapses in recent years) to post about investing and the markets. Here’s reality. It’s Saturday and the more cyber-astute are reacting to and recovering from Heartbleed, a phenomenal security hole in the Internet. Finding such a hole in the Internet is like finding out that a business couldn’t trust the electricity, water, and sewers to keep working; and that for the last two years sparks from the wires were scorching the walls, drips were rotting the foundation, and messes were piling up in hidden corners. Maybe everything is fixed, but someone’s going to have to go down into that basement and make sure – and be prepared for anything, (like Heartbleed’s cousin?). This can lead to a bit of insecurity, and investors don’t like insecurities.

The Internet created modern commerce, but not intentionally and not alone. The Internet existed for years doing what it was designed to do, connecting up various organizations so they could send data around without having to create a tape and drop it in the mail. As more people began to play with it outside of work, it blossomed while being derided as trivial. There were plenty of guesses about what it could be used for, but most of the non-work activity was discussions and hobbyists. (Serious historians can slice this gross-simplification to shreds, but stick with me here.) Then came the web, and the traffic went from text to graphics. The Internet become prettier. In addition to everything else, businesses began creating pages as digital storefronts; but really nothing more than just brochures, because they were trying to get people into the malls or catalogs. Add a bit of security though and something serious like payments could happen, and did. Hello, Amazon.

Regardless of the distrust in the investment community, my investments did well in that era, and even afterwards because I trusted in the acceptance and growth in the Internet.

Aside from stock bubbles and revolutions within industries, the Internet has grown because it has become more secure. We rely on online transactions for shopping, but also for paying bills, investing, signing contracts, talking privately, and now for storing our files in the cloud. Heartbleed proved the immaturity of the system that we’ve come to depend on and take for granted. If you can’t trust password protected accounts what can you trust? And, if you can’t trust the Internet are you prepared to retreat to paper, pen, envelopes, stamps – or even driving to the store and being limited to what they have in stock?

Despite any damage to trust in Internet transactions, businesses based on online commerce will continue. There may be a sudden spike in the demand for digital security specialists, but we’ve reached a new norm. We’re as likely to abandon the Internet as abandon electricity.

The trend I am watching is the general acceptance of diminished trust. Financial institutions lost their veneer when we saw the risks they took in the financial markets. Government shutdowns primed us to consider the possibility of losing our central authority. The Vatican continues to deal with its scandalous priests. Current economies clashing with political wills are challenging the primacy of various currencies. Tens of millions of shoppers found that their credit cards were compromised by people expending very little effort. And now, Heartbleed. I’m looking for the trend that will reinforce trust, but I haven’t found it. (The effect of writing on the writer. Having written this paragraph I noticed that the paper covering my computer’s camera had fallen. A few months ago I saw the camera light go green for no reason. Pardon me as I put the paper back in place.)

It is very easy to get scared by staring at the imperfections in the system. I definitely have concerns, but I know that my best plan is to assume everything will return to normal because we rely on this new way of living to the point that we can’t go back without trauma.

I believe it is also wise to be very aware of the imperfections in the system, and because trauma can happen. People taking on the challenge of actively managing their personal finances are to be commended. Our society is based on a currency economy. It certainly isn’t barter. But, assuming that everything will stay the same and always work ignores one of the most powerful tools available to everyone, diversification. What if online transactions couldn’t be trusted, even if for a while? What if online communications weren’t secure? What if the predominant currencies lost their dominance? Only the wealthiest have sufficient resources to cover every contingency, but at least the rest of us can take some steps to cover the contingencies we consider most likely.

Here are some of my Personal Diversifications: (in addition to diversifications within my portfolio, of course.)

  • One of the benefits of living simply is that I am less tied to the various aspects of societal infrastructure. I can do a lot with just a bicycleJust Keep Pedaling.
  • I live in a rural area where plenty of folks are happy to grow and sell food. I’d like to live even more simply by living in a house that could go off-grid. We lose power here often enough that secondary power and heat are normal parts of conversation.
  • As much as possible, I buy things that can do more than one job; and if something only does one thing I better need that frequently or in an emergency.
  • Through necessity I am generating income by relying on various skills: project management, strategic planning, social media, speaking, teaching, writing, etc. Much better than only having one skill.
  • I’ve even shopping around for crypto-currencies as a diversification against the US dollar. Why not?

Trust is under assault. If the NSA didn’t know about Heartbleed, then the NSA is not living up to their reputation – and maybe not even their mission, goals, or budget. If the NSA did know about Heartbleed, then by no saying or doing anything publicly then we may doubt their intent. Did Heartbleed reveal the NSA as incompetent or as immoral? In either case, there’s less reason to trust the NSA. Or maybe, trust was always under such suspicion but it wasn’t until we had an instantaneous and ubiquitous communication medium that we could hear each other’s doubts.

In the meantime, my stocks await a positive catalyst that I trust will arrive and I’ll continue to investigate the best way and time to diversify into a crypto-currency – ironically trusting to the very Internet that is a little less trust-worthy now.

Posted in Uncategorized | Tagged , , , , , , , , , , , , , , , , | 1 Comment

Tax Inequity Increase

I paid lower taxes when I was rich.” I said that last year. This year proves it out even more. Income was down about 40%. Income tax was up about 40%. I was traumatized by the numbers. Surely our system isn’t that dysfunctional; especially when approaching the poverty level. Surely I was wrong – and I have plenty of friends in similar situations to prove it, at least to me. There is a bit of good news but it only became apparent after downing a stiff drink and then venting with a dear friend who understands the situation too well. Maybe things will get better.

Was the first governmental conversation about income tax overly simplistic (the more a person makes the more they’re taxed because they’re more likely to afford it), or did they imagine the loopholes and byzantine paperwork to appease a draconian authority (fill out this form but attach this schedule if the worksheet produces a number in excess of the value on the appropriate table)? It must’ve seemed simple at the start. Maybe it was.

Really, I can understand the appeal of an income tax, but the reality of it has bizarre consequences.
I make a mistake in the govt’s favor I’m a chump and they’ll happily take my extra money. If I make any little mistake in the other direction, I’m a criminal.“*
A math mistake, putting a number in the wrong box, or misinterpreting arcane language across reams of instructions carries the fear of being charged with a federal offense.

When I had far more than enough income and net worth, I trusted my tax preparation to a professional. She was honest and properly pedantic, and worked through W-2s, real estate rentals, stocks, options, and miscellaneous. During my temporary, early semi-retirement my taxes were so simple that I could do them because I had no income. Make some money by making one or two stock trades per year was easy in many ways, including the paperwork. After I bought my house, and then decided to sell books and photos I used software (TurboTax) to work me through the details. Then the Triple Whammy hit. I have been working several backup plans simultaneously since. None of my efforts have succeeded comfortably, but all combine to maybe make enough to keep my house. Unfortunately, having such a diverse set of incomes means many more forms. I relinquish control to the software because properly understanding the requirements for services, retail, wholesale, royalties, etc. would require so many hours that I could probably qualify as a tax preparer.
filing taxes is a money losing proposition“*
just found out I’m making about $6.00 an hour and working my heinie off besides. Owning my own business is not all that it’s cracked up to be.“*

From what I hear, the job market is improving. What I see is many friends, unable to get hired (in many cases despite multiple degrees and phenomenal work ethics) turning instead to entrepreneurship. I submitted job applications for two years and only received one interview for a full time position – and they even admitted that they didn’t plan to hire me, but they wanted to meet the person with such an amazing resume. Trust in the conventional job market has faded, just as trust has faded in many of our institutions and conventions.

Here’s where trying to get ahead when you’ve fallen behind puts you further behind.

Welcome to something I’ve skimmed past in the past, but ran hard into this year: self-employment tax. I don’t understand how it operates but I know that, because my business’ profit margin dramatically improved I ended up paying more in self-employment tax than I paid in total for the previous year. As I said at the top, “Income was down about 40%. Income tax was up about 40%“. Part of the reason income was down was that much of the early income came from early withdrawals from my IRA, which is now seriously depleted.
According to another friend,
I’m better off earning $20K than $36K. at 36 I owe $4000 or more. Makes me sick.“*
The folks that considered themselves “lucky” were the ones who could claim large business losses.
only reason we lucked out this year is because of business losses“*
Though, it doesn’t always work out that way.
we are getting a little back, but the amount dropped significantly when I put in my little business loss…a loss…. I’m still trying to wrap my mind around that.“*
Making sense of a dysfunctional system is a waste of time, and most of these hard-workers don’t have that extra time.

One of the tenets of the American Dream is that good, hard work will be rewarded. We encourage people to work their way out of trouble. But it is while working hardest that taxes hit hardest. I worked hard enough at Boeing that my early retirement was largely encouraged for health reasons; yet, I work harder now. Corporate life also comes equipped with professionals responsible for properly accounting for withholdings and reporting. Tax season rarely held a negative surprise. When I worked the least was when I was comfortably living off my investments. (Though, for a while there I was doing nothing much for pay, but working 32 hours a week on charities. So much for lounging.) Living off investments can make life balance very easy. Trade once or twice a year, live off the proceedings, and match losses to gains. There were several years when I had two or three times my current income and paid less than a few hundred dollars in taxes. I’d like to get back there, but I wonder how the government can function under such a system.

Entrepreneurship is discouraged enough that a common chorus is a desire to return to the corporate world, just to simplify life.
When I complained about taxes I’m told to “get a better job”.“*
I got royally stung when I tried the non-S corp route. My taxes were over double previous years. You probably get that, right? I’d rather do the corp dance than see that situation again.“*
Of course, the entire issue started because better jobs weren’t available, despite the news reports and economic data.

If the system is flawed, change the system. It’s our country, right? We should be able to do that.
The waste of humanity that is our income tax system. We need a flat tax.“* – David Nelson (and with his talents I’m surprised he hasn’t single-handedly made that happen)
We need to repeal the 16th Amendment, make the states pay federal taxes… and start following the 10th amendment.“* – Peter Jungmann (and he has a plan to make it happen)

So, where’s the good news? At least for me, the good news is that last year I had to use my credit card to pay my taxes. This year, if I scrape around in various accounts and only pay the minimums on some bills, I might, might be able to pay in cash. Of course, some of the cash will come out of my skinny IRA which will kick off a tax penalty to be paid next year, but well, oh well. The taxes will get paid, then the health insurance (if I still have it), and then the trial payment for the mortgage – oh yeah, and incidentals like food and gas and . . . But hey, it is a step in the right direction. My business is growing (want to be part of the growth? hire me for some strategic planning or program management), and the increased revenues and increased profits will mean – increased taxes – and maybe enough left over to get ahead after falling so far behind.

* (Quotes courtesy of a very active social media response on Facebook with some comments on Twitter. Thanks to everyone who participated.)

Posted in Uncategorized | Tagged , , , , , , , , , , , , , , , , , , , , , , , | 1 Comment

Googly-eye-ing Disney And Projectors

Smartphones are it! So are tablets. So were laptops. So smartwatches and eyewear and wearable computers shall be. So we can be proud we’re working the trends. You ain’t seen nothing yet, and when the next thing shows up it may look like nothing to everyone else, but the wearer will see a different world. I tried on Google Glass, listened to the pitch, saw a presentation from Disney Research and realized the world is about to change again – and not only because of Google.

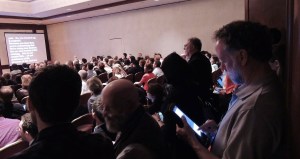
For the first several days in April I attended the Museums and the Web conference,

photo courtesy of Andrew Lewis (@rosemarybeetle)

photo courtesy of Andrew Lewis (@rosemarybeetle)

a conference for museum operators and staff that are wise enough to know that marble columns, white walls, artifacts, and little placards aren’t enough in 2014. Visitors expect to walk in with their smartphones in hand, take photos to share regardless of copyright, and are more likely to access wikipedia than a curator or docent. I was there as Project Manager for the Virtual Museum of the History of Computing in Learning and Education (HCLE). Smartphones in our museum? Our museum will be in the smartphone. No red velvet ropes. No dusting required.

Most of the presentations were from museum people talking about museums, visitors, and technology. Just like in education, where the teacher’s role and control changed because of computers (which is one of the primary motivations for our museum), museums’ roles and controls are changing. (I think they have a lot to learn from the educators, but then I have a bias.)

Two presentations that came from the technology side pleased the geek in me.

Eric Brockmeyer from Disney Research (Pittsburgh) gave a sweeping show about using technology that brings the animated characters out of the movies and into the real world. Rapid prototyped versions of the characters are equipped with robotic parts, LED light-piped eyes that track the motion of the visitor; even ways to save and store and listen to sounds generated by, in, and around plants. A quick segment, maybe not even a minute long, showed two pico-projectors working in concert to as part of a game. Investors in MicroVision, like me, know the potential for pico-projectors; and we’ve frequently cautioned our prognostications because we realize the company’s success may come from applications we haven’t imagined. These two pico-projectors played a new trick (at least to me). One used visible light. One used infra-red. The visitor only sees one, and may not know how the other one adds depth and intelligence to the interaction. Robots aren’t just for building cars. LEDs aren’t just for lighting the living room. Plants may finally get a voice in a language we can hear. 3-D animations may walk across a table and play with your drink. (A sobriety and sanity test I just invented.)

Google brought Google Glass, their revolutionary eyewear that is so well-tested that I’ve seen about a dozen in demos and in real life.

Google Glass - so common there was one in the front and one in the back

Google Glass – so common there was one in the front and one in the back

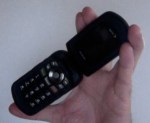
The presenters made a good case for how wearable computers will change the way we interact with the world and each other. Previous wearable computers were bulky, required belted joysticks and keyboards, and large CPUs and battery packs. Miniaturization has shrunk much of the hardware into a pair of glasses and a smartphone. (One presenter mentioned that we all have smartphones. Ha! My mobile is a Kyocera flip phone, Photo on 2014-04-06 at 18.42 and I only have it because Sprint pulled the antiquated tower hardware that could actually talk with my previous, perfectly capable flip phone.) To me, the main enabler was the control being voice and a finger swipe rather than hand-controllers. Free the hands and increase the interaction, museum or not. Add sensors and the interaction reaches other sensory dimensions.
After the presentations I quickly roamed the exhibit hall. There was a lot to do, so I couldn’t spend much time with the vendors; except for my friends over at STQRY. Maybe it is easier to chat because any business from HCLE is theoretical or years away. They make mobile apps, or apps for mobile devices; which means they are central to the conventional museums’ conversation and conversion. And they had a Google Glass tester, which I happily wore. If they expected a bigger reaction, I may have disappointed them. I’ve seen such devices before. As friends I asked them about the potential I have seen with pico-projectors coupled with hands-free computers.

Pico-projectors don’t just act like another screen. They can project. They can read. One application is a computer that replaces the screen with one pico-projector and the keyboard with another. Computers can take the next step from room-sized to desktop to laptop to handheld to worn to – I don’t know, sewn in? One of the consequences of MicroVision’s technology is that, while it is projecting an image it can also capture finger movements. Hand swipes on an iPad can become hand swipes in mid-air, which may look strange but are less obtrusive than people talking on cell phones. A computer becomes a device the size of a coffee cup, or smaller: CPU, memory, power, and two projectors the size of thin mints.

That doesn’t change the museum experience until someone takes the extra step and makes it wearable. Keyboards in air, that are only visible to the wearer. Displays that are transparent, and that can overlay the world with data or digital graffiti (which is far preferable to real graffiti). If the glasses are indistinguishable from spectacles, then there is no control over what the visitors sees or accesses. A virtual world overlaying the real world means white walls have their place. Or shares, because this can also improve the appeal of museums. A visitor having a revelatory experience can immediately share it to their social network without interfering with the rest of the visitors. Awareness grows. Culture spreads. Museums increase their relevance.

Such a vision may be going too far for some conversations. Yet, the speed of the technology will not be changed to accommodate the speed of a museum’s evolution. The revolution will walk in the door; and it won’t just happen in museums. Classrooms, conference rooms, offices, even around the home will work best if they work with the fact that people will use their finger tips to call up data from anywhere without intruding on someone else’s life. Though, casual observers may find it fun to watch a bunch of people wagging fingers at each other. And of course, the wearers may have a grand time in the virtual world making fun of the computationally naked folks.

As an investor in MicroVision I am encouraged, at least for the technology and hopefully for the company. Their proprietary technology solves many problems simultaneously while adding features: always in focus, even on moving curtains; biometrics, by possibly conducting real-time retinal identification; and evidently the possibility to extend beyond visible light, to do . . . ?

Many of the technological changes are discussed as extrapolations, dreams of possibilities a decade away. Pico-projection has been in work for decades and may disrupt technologies and our world, even institutions like museums, within years – and for all I know, months.

About ten years ago I tried on a wearable computer. MicroVision actually released it as a product. The Nomad was a cigarette-sized box clipped onto the brim of a baseball cap, with a hand controller worn on a belt. The display was only in red, aimed at too niche of a market (auto mechanics), and wasn’t designed for manufacture or repair or profit. Yet from what I recall, Nomad’s image was clearer than Google Glass’. Maybe that’s just my age. I also recall the color prototype that played images directly onto the retina, dramatically decreasing power requirements while also making the display readable in daylight (except for maybe in the desert at high noon.) Nomad’s controller was more responsive because it didn’t rely on wi-fi. But it didn’t look nearly as nice (which is a very sad statement for both) and didn’t have Google’s publicity and name spreading the word.

I am glad to be alive as we live through this era, just like I find it unique to have lived through an era that so dramatically changed education and the rest of my life. Just like before though, people become comfortable with the new speed of change that follows a disruption – and then the next disruption hits. I don’t know if it will be from Disney, or Google, or MicroVision, or someone else, or some combination of them; but, I am more convinced that it is about to happen. I hope I can afford to buy in and enjoy.

Posted in Uncategorized | Tagged , , , , , , , , , , , , , , , , , , , , , | 1 Comment

The Day After The ACA Deadline

The deadline passed. Obamacare, ACA, the Affordable Care Act, the great grandiose pack of wonders or horrors depending on your point of view reached and surpassed its quota of subscribers. The wonders and horrors are already being touted. It sounds like the day after someone gets their first car; do you want to hear about the grand and glorious places they can go, or do you want to hear about the cost of gas and the vehicular accident rates? The systemic economic statistics won’t be available for years, but those of us that signed up by the December deadline have months of personal data to back up our stories.

To those who’ve shared their stories and their data with me, don’t worry, discretion will be maintained.

To those of you just finding this blog and my story, here are a few links along the way.

To those of you who’ve been following my story, the slapstick fun never seems to end.

But wait. My pratfalls, banana peals, and whoopie cushion moments were supposed to be over. I finally got everything arranged. Provider chosen. Payments arranged. Premiums paid. You are a silly person, or maybe it is just me.

First I couldn’t log in. Then I got coverage but at a 60% increase. Then it turned out I probably didn’t have coverage. Then I got coverage and got the tax credit and the rate came back down to my pre-ACA rate plus ten dollars. Then I didn’t get billed, and only resolved it within hours of the deadline.

Welcome to March. I expected a bill in the mail because the fine folks at Washington Health Plan worked hard to set that up for me. I trust technology more than many, but enough had gone wrong that I wanted paper delivered that I would respond to with an envelope, a stamp, and a paper check. Ah, but an email came in that looked like an auto-pay, but hey, at least it was paid.

Or not. I watched my bank account and the money hadn’t been withdrawn. Open the email, click on the link, spend too much time and energy logging in and having to reset passwords again, to learn that the email has a link to the bill, not to a payment. I was supposed to print the bill myself. And the payment wasn’t due at the end of the month. It was due a week earlier.

The regular mail wouldn’t work in time. Even Express Mail doesn’t take a letter stamped at 10pm on the 30th and get it to its destination by the 31st. Bang my head slowly, otherwise it hurts too much – and for all I knew and know, I don’t have coverage.

Ah, but a glimmer of hope. There was a Pay It Now button, which I clicked, where I paid, and received a receipt. So, I don’t know if I have coverage, but I do know that they have my money. One spot of good news is that my premium dropped 10%. One spot of bad news is that friends tell me mistakes in the paper payment process take months to resolve.

Have you caught on to what’s missing in this discussion of health insurance? There has been no mention of health being cared for. No doctors visits. No prescriptions. Just payments in money, time, and emotional reserves.

Let us celebrate millions of people signing up for health care. Authentic anecdotes tell of people finally receiving medication, going to the doctor, not being bureaucratically limited by pre-existing conditions. But almost all coverage includes co-pays (usually reasonable), deductibles (which is $2,000) in my case, and some portion of the doctor’s visits, tests, and procedures.

I believe that healthier people will systemically decrease the cost of health care (duh, and yet that point isn’t raised enough), will increase the productivity of the nation, will free up ideas and time and energy and money to improve almost every aspect of society. But we aren’t talking about free healthcare. We’re talking about health insurance that costs as much as some people are paying for food, or housing; and those are the people who had to make tough choices about which bills to pay which may have been why they weren’t insured at the start.

Here, in the first days of April, I don’t know if I have insurance. Yes, I know it will be easy to find out. Just call. But I’ve learned that any such call can easily take two hours, and two hours chasing electronic ghosts is two hours I’m not billing hours that pay my bills.

Signing up for healthcare is simple. Enough of my friends have proved that. Maybe my issues have to deal with overwork, which could also be said about many of those who’ve signed up.

Personal finance is inherently simple. Saving for retirement is simple. Spend less than you make and invest the rest.

The simple stories suggest simple solutions. There are details that don’t fit in short articles, or even in episodic blogs. Especially in healthcare, every situation is different because we are all unique.

As the March 31st deadline approached I could tell that a lot of people were looking for help in unofficial places. My blog traffic grew every day until it set records. The most popular posts were of my experiences trying to sign up, pay, and confirm my health care coverage. Considering that healthcare tends to be tied to a region, there were a lot of people in Washington State looking for help; and Washington State is one of the better run systems (from what I’ve heard.)

I suspect I’ll know even more if I ever actually visit a doctor. In the meantime, I’ll continue my version of eating right, exercising, trying to get plenty of rest and fluids, and maybe getting a massage or visiting an acupuncturist. No insurance required.

Posted in Uncategorized | Tagged , , , , | 1 Comment

Shopping For A Coin

I want to buy some money. That can sound like a silly idea. “Hey, how much will you charge me for that dollar?” And, no, I’m not about to go on about trading in currencies. That’s been going on for centuries. The money I want is something new, and I don’t want to trade it. I want to use it. In the last few years cryptocurrencies have arisen. Have you heard of Bitcoin? It isn’t alone. People are searching for alternatives to dollars, pounds, yen, and anything printed by a nation. They couldn’t find what they wanted; so, they created what they sought. Now comes the hard part, making it work. The hard part for me is learning more. The easiest way to learn? Buy a Bitcoin or one of its cousins and see what I can do with it. Let the shopping begin.

The dollar and the Euro continue to rule the world of finance. All the cryptocurrencies added together are still worth less than a corporation like Starbucks. Bitcoin is not threatening Fort Knox. But the recent turmoil decreased confidence in the conventional financial system. Some people want to disassociate themselves from the economy that includes the military-industrial complex, fossil fuels, and corporate egregences. Movies like Money & Life illustrate some of the unsustainable assumptions behind the current system. My concern comes from the systems analyses that suggest the system is dangerously unstable.

Cyptocurrencies have been designed to answer many of the concerns. They aren’t associated with governments or banks. They can’t be printed at whim the way governments print more money. The transactions have the potential to be more secure, more secret, more reliable, and harder to abuse (though recent events have proved that no system is perfect). They are decentralized, that scary notion that power isn’t concentrated; which is also appealing to some.

There is plenty of precedent. History is filled with non-governmental currencies. The dollar didn’t become the standard US currency until 1863. As a society we’ve yet to find the perfect economic system, and alternative currencies are evidence of our attempts.

There is also plenty of ignorance, which is where I am.

Despite my ignorance I am interested because I am a curious fellow and because enough of the concerns mentioned above have convinced me that a bit of diversification is a good idea. Stocks, bonds, mortgaged real estate, and most financial instruments all have the same single point of failure. If the dollar becomes unstable, they become unstable. As an engineer I don’t like unstable systems that have critical single points of failure.

Bitcoins drew my attention over the last few years. Oh, if I had only bought back then … Last month I wrote about my early interest in it. A few weeks later the news broke of the big Bitcoin heist. I’m glad I waited. I’d like to claim wisdom, but I was too busy to get around to making the transaction. The subsequent news items and the charts convinced me that Bitcoin may be in a bubble. Just because one coin is askew doesn’t mean the others are too. I’d heard of litecoin, peercoin, and dogecoin; but the coin that inspired me to do more than study is auroracoin.

I like Iceland. They just announced a cryptocurrency that is for their citizens, and to make sure their citizens all have an equal opportunity within the crypto-economy they gave everyone the same number of coins at the same time. Instead of early adopters stepping in and making the equivalent of a land grab, they gave everyone a stake and an equal opportunity. Very cool. (I also like what they did with mortgages.)

Auroracoin and the rest have a basic problem. Everyone knows how regular money is used to buy things, but crypto-currencies are novel enough that only those with the greatest incentives have been exercising them. Unfortunately, that has frequently been the illegal set. For cryptocurrencies to succeed they have to become useful for buying food, clothes, shelter and paying for utilities. Supply and demand are flirting with each other, but it is still like boys and girls sitting along opposite walls at a high school dance. Very few are making that first move.

I may have a unique opportunity to delve in, learn more, pass along what I learn, and maybe even use such a currency for something that is legit. I already have a virtual currency from Second Life called Linden Dollars.

My house in Second Life

The view from my house in Second Life

I’d like to diversify those dollars, so why not a non-Second Life cryptocurrency? I live in Washington State, which just legalized marijuana (though it isn’t on sale for recreational use yet). Marijuana shops have high enough hurdles when it comes to handling money through regular banks that another cryptocurrency has sprouted call Potcoin. Maybe exchanges can be made.

As I’ve mentioned, my passion is for people and ideas. I enjoy helping projects and new ideas. (That’s why I enjoy consulting.) This is a new idea that I may be able to help merely by buying a coin. And it may help me by placing me at least one small step closer to diversity in currency. My next step? Shopping for money. Always something new to learn, eh?

PS Something I recently learned is that some coins are gaining popularity as a way for readers to tip bloggers. Want to leave a tip whether I buy a coin or not? I’ve got a PayPal account. (tetrimbath@whidbey.com)

Posted in Uncategorized | Tagged , , , , , , , , | Leave a comment

Borrow A Bowl For A Bash

Borrow a bowl! Why yes, I’d be happy to. Why borrow a bowl? Because I had something to celebrate. A community helped, which meant the celebration would be more than just me. That sounded like a party, a bash. Got problems? It is good to have a supportive community. When’s the best time to build community? Before you need it. When’s a great time to reward community? After it has come together without expectation of reward. And repeat.

The good news is that it looks like I get to keep my home. Maybe. Really I am in a trial period that may result in a mortgage modification that may have a probationary period, but those are details. As long as my business can generate enough income (and a few extra hours consulting with paying clients helps a lot ), I’ll probably end up with a modified mortgage that is about half of the original. This was something to celebrate, particularly with the community of friends who’ve helped me through.

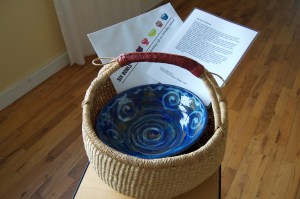
One of my clients is building and reinforcing community with a simple idea. The Six Bowls Project, instigated by Penny Bauer, is ingenious. Six bowls made by local potters, carried in artisan baskets, tucked in with words from local poets, and hosted by local businesses are borrowed for weekend events for free. DSC_4231 Borrow a bowl. Carry it home in the basket. Invite some friends around a community theme. Share the literary contribution. Share the food. Then clean the bowl, share the stories, and return the bowl and the basket and the words for the next person. Then, after six bowls have catalyzed a year of stories, auction off the bowls for a charity that helps clothe and feed the community. Brilliant. My role? Be a sounding board, then feed the Facebook page daily. I get paid to pass along stories. Nice job, even if it is more editorial than managerial.

So many of the stories are parts of grand ventures: trips to Africa, groups that have been together for years, generations supporting other generations covering every age. My story was about the fact that I could stay put. But too many others are embroiled in that same struggle that a bit of good news should probably be passed along. (And a friend just told me he may be able to save his house by learning from what I’ve gone through. Imagine that feeling.) The email invite list was long (and incomplete as always) and the party was to be as simple as ever.
Been to my parties before? Same plan. I’ll put out some munchies and wine. No need to bring anything else but if you bring something then you know there’ll be something there you want to eat or drink.
Casual. My place isn’t that fancy (though I think the view is marvelous and a good reason to get here before sunset). Finale Mostly chit-chat, and usually some dancing before the end. You folks are entertaining enough that there’s no need for games and such. If you want to dance, I’ll have a boombox and some cds, but you are welcome to bring better equipment and music.

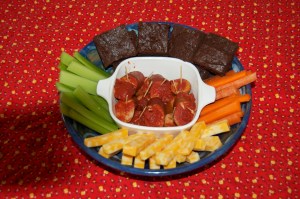
But what to put in the bowl? So many of the other stories have impressive recipes. I love to cook, but those recipes set a high bar. Then I looked at what came with the bowl. Patricia Duff wrote the meaningful backstory to the bowl. (Every bowl gets some bit of literary eloquence.) She called it an Everyman bowl (by Lyla Lillis). Cooking for every one is difficult because we are a diverse crowd by choice and necessity. So, I decided that, rather than try to navigate dozens of diets, I’d put enough different things in the bowl to please (almost) everyone. DSC_4236Sausage in the middle, flanked by carrots and celery, fronted with cheese, and backed with brownies. (By the time the party started I had to switch out the sausages for smoked salmon. Long story. Burp.) And if no one ate them, I’d have good leftovers.

The bowl wasn’t alone. There was also the basket which was empty without the bowl, so I dropped in a sign: “Fill the basket with ideas.” Few had the time to write anything, but one idea was dear. “We should start a progressive party – take this to someone else’s house every couple of hours.” Marvelous. Maybe next time.

The party was so good that we didn’t get around to dancing. (Though I admit to missing that.)

Then it was time to bundle the bowl back into its basket (after washing it). Hang onto the memories of the party and my friends and what they’ve helped achieve.

DSC_4246

Community is built from within and by more than just one. Penny’s idea for Six Bowls is simple and powerful; and succeeds because so many people participate. Other individuals like, Drew Kampion of Drewslist, work on their own spending incredible time and effort creating vital services that ultimately reciprocate (and if you’re on drewslist have you sent him a donation lately?). Organizations like Good Cheer are more like what many expect, large non-profits officially providing an otherwise non-existent safety net. The beauty and the power of such support come from the efforts of individuals taking simple ideas, filling needs, and leaving egos behind. Most of their work is unacknowledged off-island. Do the same work in some urban environment and end up on the national news. But here, we get to see their efforts first hand, and appreciate them greatly.

Here we get to see what community can do for community – and it always starts with individuals.

Frugal people understand that personal finance is about value, which only sometimes involves money – though mainstream media makes it sound like money is the only thing of value.

If you’re on the island; borrow a bowl, donate to Drew, cheer on Good Cheer. If you’re not on the island; look around to see what’s there, and if nothing’s there know that you can make it yourself and make community at the same time.

Nothing is certain so it makes sense to celebrate what we can, how we can, and include as many as we can. And maybe there will be more dancing.

Posted in Uncategorized | Tagged , , , , , , , , , , , , , , | 1 Comment